Best Rewards Credit Cards for Beginners in 2026: Cash Back Without Annual Fees
- Primary Signal: Best Rewards Credit Cards for Beginners in 2026: Cash Back Without Annual Fees
- Overview: Best rewards credit cards for beginners in 2026: no-annual-fee cash back cards, how to choose, and how to use them safely....
- Verification: Analyzed and compiled by FreeFortune Rewards editorial monitoring desk.
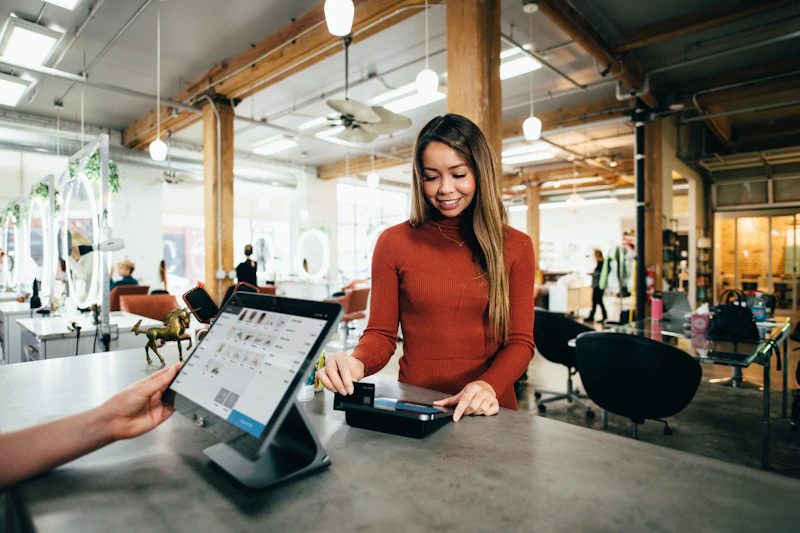
A good rewards credit card pays you for spending you already do, and the best beginner cards charge no annual fee, so the rewards are pure profit. The catch is that cards only pay when you pay in full every month: interest at 20% or more wipes out any cashback many times over. This guide compares the best no-fee beginner cards and how to use them safely.
Flat Cash Back: The Simplest Start
A flat 2% cash back card is the best first rewards card, because it pays the same on every purchase with no categories to track. It suits beginners who want one card for everything and a predictable return. Look for a card with no annual fee, no foreign transaction fee if you travel, and a welcome bonus that pays after a modest spend. The return is small per purchase but adds up to hundreds a year on normal spending.
Category Cards: More Back Where You Spend
Category cards pay 3-5% on specific spending like groceries, gas or dining, and 1% on everything else. They earn more than flat cards if your spending concentrates in one category, but they need tracking: a groceries card earns nothing extra on electronics. Beginners should start with a flat card, then add one category card for their biggest spending area after six months of good habits.
Welcome Bonuses: Free Money With Rules
Most beginner cards offer a welcome bonus, typically $150-200 after spending $500-1,000 in the first three months. The bonus is real money, but only take it if you would spend that amount anyway: manufacturing spending to chase a bonus is how people fall into debt. Read the terms: some bonuses require the spend in a single month, others spread it over three.
The Rules That Keep Rewards Profitable
Pay the full balance every month, without exception. Set up autopay for the full statement balance so a forgotten payment never triggers interest or a late fee. Keep your credit utilisation under 30% of your limit, because high utilisation hurts your credit score even if you pay in full. Never use a rewards card to buy something you would not buy with cash: the reward is a bonus, not a reason to spend.
Building Credit While You Earn
A beginner card also builds your credit history, which matters for renting, car insurance and future loans. Keep the card open for at least a year, use it regularly, and pay on time every month. After a year of good history, you can ask for a higher limit or a better card, and your score will reflect the discipline. Rewards are the bonus; the credit history is the real prize.
Upgrading Your Card Over Time
Your first rewards card is a starting point, not a destination: after a year of on-time payments, your credit score will have improved, and you can ask for a higher limit, a better card, or a product change to a card with higher rewards. The upgrade path is usually flat card first, then a category card for your biggest spending area, then a travel card if you fly often. Never close your first card, because its age helps your credit score, even if you stop using it. Keep it open with a small recurring charge, and let the history work for you.
Key Takeaways
- A flat 2% card with no annual fee is the best first rewards card - Category cards pay 3-5% where you spend most, but need tracking - Welcome bonuses of $150-200 are real, but only if you would spend anyway - Pay in full every month: interest wipes out any cashback
Frequently Asked Questions
What is the best rewards credit card for beginners? A no-annual-fee flat 2% cash back card. It pays on everything with no categories to track, and it builds credit history while you earn.
A rewards card pays you for spending you already do, but only if you pay in full every month. Start flat, add a category card later.
More from FreeFortune Rewards